Dealing With Hidden Structural Damage: A Homeowner's Guide
Table of Contents
What Counts as Hidden Structural Damage in a House
Signs of Structural Damage in House You Should Never Ignore
How to Document Hidden Structural Damage for an Insurance Claim
The Structural Damage Insurance Claim Process, Step by Step
Hiring a Structural Engineer for Home Inspection: What Homeowners Need to Know
When Your Claim Is Denied, Underpaid, or Stalled
Preventing Hidden Structural Damage Before It Happens
Frequently Asked Questions
Last Updated: October 4, 2026
What Counts as Hidden Structural Damage in a House
Dealing with hidden structural damage starts with knowing what you're actually looking at. Hidden structural damage is any harm to a home's load-bearing parts that isn't visible during a normal walkthrough. It sits behind drywall, under flooring, or inside the foundation.
Common examples include:
Cracked or shifted foundation walls
Rotted framing behind fresh paint
Damaged floor joists under carpet
Separated roof trusses in the attic
The tricky part is that cosmetic fixes often hide the real problem. A fresh coat of paint over a water stain tells you nothing about what's happening behind it. That's why a proper professional assessment matters more than a quick visual scan.
Signs of Structural Damage in House You Should Never Ignore
Signs of structural damage in house settings usually show up as small clues before anything dramatic happens. Catching them early saves money and stress.
Watch for these red flags:
New cracks in walls, especially near door frames
Doors or windows that suddenly stick or won't latch
Uneven or sloping floors
Gaps where walls meet ceilings
Bowed or sagging rooflines
A musty smell that won't go away
Visible sagging in the attic framing
One or two of these might be normal settling. Several together usually point to something bigger. Panel gaps around windows and misalignment in door frames are two of the most reliable early warnings.
Watch Out Painting over cracks or patching drywall without checking the cause is a common mistake. It hides the symptom, not the problem, and the damage keeps spreading behind the wall.
If you spot these signs, don't wait. Structural integrity doesn't improve on its own.
How to Document Hidden Structural Damage for an Insurance Claim
Documenting evidence is the single most important step in any structural damage insurance claim process. A weak paper trail is the fastest way to a denied or underpaid claim.
Here's what to gather:
Date-stamped photos of every crack, stain, and gap
Video walkthroughs of each affected room
Receipts for any emergency repairs already made
A written timeline of when you first noticed each issue
Notes from any contractor who has looked at the damage
Store everything in one folder, digital or physical. Label each photo with the room and the date.
Many homeowners find that a professional assessment strengthens their file. An engineer's report carries more weight than homeowner photos alone. It gives the adjuster something concrete to work from.
The National Association of Insurance Commissioners consumer guide offers free resources on documenting property claims correctly.
The Structural Damage Insurance Claim Process, Step by Step
The structural damage insurance claim process follows a clear path, but the outcome is usually decided at two points: the adjuster's inspection and the settlement negotiation. Knowing the mechanics at each stage is what separates a full payout from a lowball offer.
Report the damage to your insurer right away. Most policies require prompt notice. Delays give the insurer grounds to question whether the damage pre-dated the loss.
Document everything before any cleanup begins. Once debris is hauled away or a wall is patched, you lose the evidence that supports the scope of loss.
Request a professional inspection. An engineer's report establishes causation and scope in writing, the two things an adjuster cannot easily dispute.
Submit your claim with all supporting evidence. Include the engineer's report, dated photos, video, receipts, and a written timeline.
Meet the insurance adjuster on site. Walk the property with them and point out every documented issue. Adjusters work from a scope sheet; if an item isn't on it, it isn't paid.
Review the settlement offer line by line. Compare it against your engineer's repair recommendation, not against what feels fair.
Negotiate if the offer falls short. Ask for a written breakdown of how each line item was calculated.
Get repairs done by a licensed contractor. Keep every invoice, supplements are common when hidden damage is found during the repair.
The adjuster visit is where claims are often won or lost. Adjusters are trained to scope visible damage; hidden structural damage by definition isn't visible, so the burden is on you to make it legible. Hand them your engineer's report at the start of the walkthrough, not after.
How to counter a low offer. A common pattern is an offer that covers cosmetic repair but omits foundation stabilization, joist replacement, or engineering costs. When that happens:
Request the adjuster's written scope and compare it to your engineer's report line by line.
Ask for a re-inspection with your engineer present so the two professionals can discuss the findings directly.
Invoke the appraisal clause if your policy has one. This is a dispute-resolution mechanism, separate from a lawsuit, where each side hires an independent appraiser and the two appraisers select a neutral umpire. It is often faster and cheaper than litigation, and many homeowners never realize it exists in their policy.
Document every phone call with a follow-up email summarizing what was said.
Step | Who Handles It | Typical Timing |
Report damage | Homeowner | Within days |
Document evidence | Homeowner | Before cleanup |
Professional inspection | Licensed engineer | 1-2 weeks |
Adjuster visit | Insurance adjuster | 1-3 weeks |
Settlement review | Homeowner | Within days of offer |
Appraisal (if disputed) | Independent appraisers | Weeks to months |
Repairs | Licensed contractor | After approval |
Pro Tip Ask your insurer for a complete copy of your policy, including endorsements. The appraisal clause, proof-of-loss deadlines, and any exclusions for earth movement or long-term seepage are all buried there, and they decide how much leverage you actually have.
Hiring a Structural Engineer for Home Inspection: What Homeowners Need to Know
Hiring a structural engineer for home inspection is the step most homeowners skip, and it's usually the one that matters most. An engineer confirms whether damage is structural or cosmetic and puts it in writing.
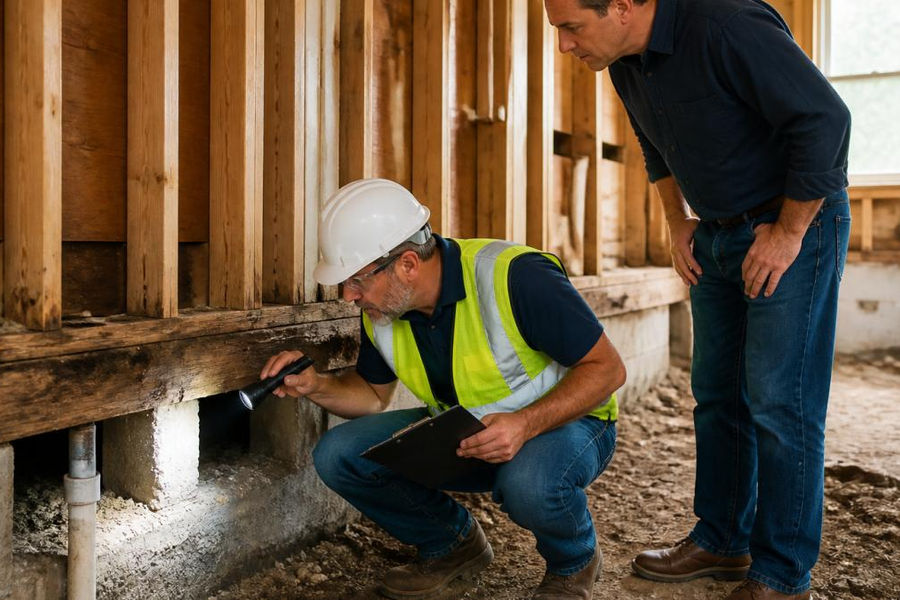
What to look for in an engineer:
State licensure and current credentials
Experience with residential foundation and framing work
A written report you can submit to your insurer
Willingness to serve as an expert witness if needed
A good report includes photos, a damage summary, and a repair recommendation. That document often does more for a claim than anything else you submit.
Ask upfront what the report will cover. Some engineers only inspect, while others also provide repair estimates. Know which one you're getting.
When Your Claim Is Denied, Underpaid, or Stalled
A denied, underpaid, or stalled claim is not the end of the road. What most homeowners don't realize is that there is a structured escalation ladder, and each rung creates a written record that strengthens the next one.
Step 1: Get the denial in writing with a specific reason. A vague denial is often a negotiating position, not a final decision. Insurers are required to state the policy provision they relied on. If they won't, that itself is worth documenting.
Step 2: Request a re-inspection with your engineer present. This is the single most effective move for hidden structural damage, because the dispute is usually about causation and scope, exactly what an engineer's report addresses.
Step 3: File a formal appeal with your insurer. Submit it in writing, reference your claim number, and attach the engineer's report, dated photos, and a point-by-point rebuttal of the denial reason.
Step 4: Contact your state's department of insurance. Every state has one, and it accepts consumer complaints about claims handling. A regulator inquiry often prompts a fresh review by a different adjuster. This step costs nothing and creates an official record.
Step 5: Consult an attorney if the amount justifies it. For a claim worth tens of thousands of dollars, a contingency-fee attorney may take the case. For smaller claims, the cost of counsel can exceed the recovery.
Legal theories that commonly apply.
Breach of contract, the insurer failed to honor the terms of the policy. This is the most straightforward claim.
Bad faith, some states allow an extra-contractual claim when an insurer unreasonably delays or denies a valid claim. Remedies can include damages beyond the policy limit, but the standard varies significantly by state.
Diminished value, if repaired structural damage lowers your home's market value, this can be pursued in some circumstances, though it is harder to prove for real property than for vehicles.
State disclosure and claims rules vary widely. Some states require sellers to complete a written disclosure of known structural issues; others rely on a property condition report or follow a caveat emptor approach. A handful impose specific timelines for insurer claim acknowledgment and payment. Before you buy, sell, or file, check your state's real estate commission and department of insurance websites, both publish plain-language consumer guides.
Watch Out Deadlines matter. Most policies impose a proof-of-loss deadline (often 60 days from the date of loss) and a suit-limitation period (commonly one to two years, sometimes shorter). Miss either and you can lose the right to recover, no matter how valid the claim.
Key Takeaway Escalate in writing, in order, and keep copies of everything. A clear paper trail is often what turns a stalled claim around, and it's the first thing an attorney or regulator will ask for.
Preventing Hidden Structural Damage Before It Happens
Prevention is cheaper than any repair. A little due diligence now saves a lot of dealing with hidden structural damage later.
Build these habits into your routine:
Inspect your foundation and attic twice a year
Fix leaks immediately, even small ones
Keep gutters clear so water moves away from the home
Check for new cracks after every major storm
Get a pre-purchase inspection before buying any home
For buyers, a preventative pre-purchase checklist is your best defense. Include a foundation check, a roof inspection, and a look at the attic framing. Ask for the accident history and any prior repair records.
Advance driver-assistance systems and modern safety features don't protect a home, but the same principle applies: catch problems early, before they compound.
Frequently Asked Questions
What qualifies as structural damage to a house?
Structural damage affects the load-bearing components that keep your home standing: foundation walls, floor joists, roof framing, and load-bearing walls. Common signs include cracks wider than a quarter inch, doors and windows that no longer close properly, sloping floors, and gaps around exterior trim. Cosmetic damage like hairline plaster cracks or peeling paint does not compromise structural integrity. When in doubt, hire a licensed engineer for a professional assessment before assuming the worst or ignoring a real problem.
Will homeowners insurance cover hidden structural damage?
Coverage depends on the cause. Most policies cover sudden events like storms, burst pipes, or fire that lead to structural damage. They typically exclude damage from long-term neglect, poor maintenance, or gradual settling. If you discover hidden structural damage, file a claim promptly and document everything with dated photos, repair estimates, and an engineer's report. If the insurer denies or undercuts your claim, you can request a re-inspection or hire a public adjuster to negotiate on your behalf.
How do I document hidden structural damage for an insurance claim?
Start by photographing and video-recording every sign of damage with a ruler or coin for scale. Keep a written log of when you noticed each issue and any related events like storms or leaks. Get at least two repair estimates from licensed contractors. If damage is hidden behind walls, an engineer's report is critical. Store copies of all correspondence with your insurer. This documentation supports your claim and protects you if the insurer disputes the extent or cause of the damage.
When should I hire a structural engineer for home repairs?
Hire an engineer when you see multiple warning signs: cracks that widen over time, floors that slope noticeably, or doors and windows that stick after a storm. Also bring one in if your insurer disputes the cause or extent of damage, or if a contractor recommends major structural work. An engineer provides an unbiased professional assessment that carries weight with insurance adjusters and can guide the scope of repairs before you commit to a contractor.
Hidden structural damage rarely announces itself. It hides behind paint, under floors, and inside walls until the cost of ignoring it gets steep. At Rapid Refurb, our licensed and insured team handles the full insurance claim process for you, from documenting evidence to communicating directly with adjusters. We manage the repairs, the timelines, and the paperwork so you can focus on your home. Get a quote from Rapid Refurb and let us take the stress out of your restoration.
Get Quote


Comments