Rebuilding After Damage? How to Upgrade Beyond What Insurance Covers (and Use Financing to Make It Work)
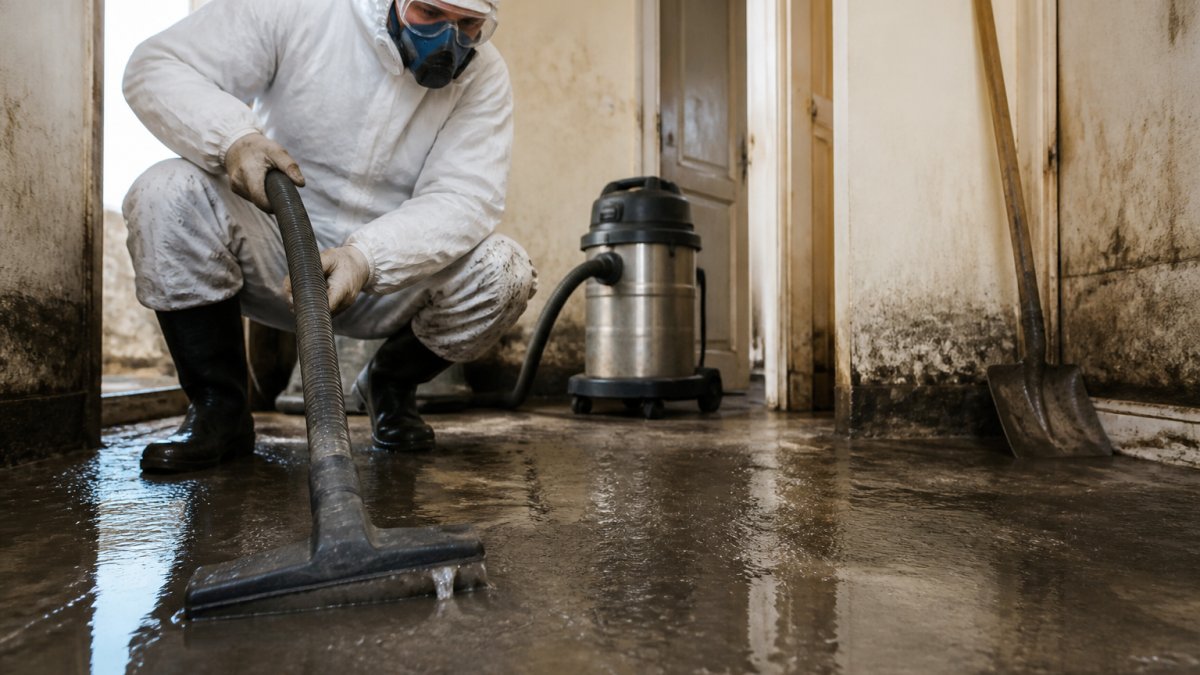
Nobody plans for a burst pipe or a kitchen fire. But once the water is dried out and the damaged materials are torn out, a lot of homeowners around Greensboro, Randleman, and the Triad find themselves standing in a gutted kitchen or bathroom asking the same question: "If we're rebuilding this anyway, should we make it better than it was?"
It's a fair question. The walls are open, the old cabinets are gone, and the crew is already scheduled. For many families, an insurance rebuild is the most practical time they'll ever have to make an upgrade they've wanted for years. The trick is doing it the right way, so your claim stays clean and the extra cost doesn't sink your budget. Here's how to think it through.
What insurance typically pays for (and what it doesn't)
Most homeowners policies are written to put your home back to roughly the condition it was in before the loss. That's often described as "like kind and quality." If you had laminate countertops and builder-grade cabinets, the claim is generally built around replacing laminate countertops and builder-grade cabinets.
Every policy is different, so your adjuster and your policy documents are the final word on what's covered. But in general, anything beyond the original scope, like quartz instead of laminate, a larger walk-in shower instead of a tub, or moving a wall, is an upgrade, and the cost difference is usually the homeowner's responsibility.
That isn't bad news. It just means the insurance money covers the "put it back" part, and you decide whether to add to it.
Why a rebuild is a smart time to upgrade
When the work is already happening, upgrades often make more sense than they would as a separate project later:
The demolition is already done. Tearing out cabinets, flooring, or drywall is a real part of any remodel's cost. During a rebuild, that work is part of the restoration.
You only live through construction once. Doing the upgrade now means one round of dust, noise, and disruption instead of two.
Materials and labor are already being coordinated. Changing a finish or fixture during the rebuild is usually simpler than coming back to rip out brand-new work a year from now.
You can fix what never worked. Maybe the old layout always felt cramped, or the bathroom never had enough storage. A rebuild is a chance to solve that instead of rebuilding the same frustration.
Keep the claim and the upgrades separate
This is the most important part. Upgrades should always be priced and documented separately from the insurance scope. Your claim should reflect what was actually damaged and what it takes to restore it, nothing more.
A good restoration contractor will help you keep it straight:
Start with the insurance scope. This is the work needed to restore your home to its pre-loss condition, based on what the adjuster approves.
Price upgrades as their own line items. If you want quartz instead of laminate, the estimate should show the difference clearly so you know exactly what you're paying for.
Put changes in writing. Any upgrade you choose should be agreed to in writing before the work begins, so there are no surprises on the final bill.
Talk to your adjuster if you're unsure. If you have questions about how an upgrade affects your claim or your payments, ask before you commit.
Keeping things separate protects you, keeps your claim honest, and makes the whole process smoother for everyone involved.
Where financing fits in
Here's where many homeowners get stuck. The insurance check covers the restoration, but the upgrade they really want costs more than they have set aside right now. That's exactly what home improvement financing is for.
Rapid Refurb offers customer financing through Lyon Financial and Service Finance. Instead of choosing between "put it back exactly the same" and "drain the savings account," financing lets you spread the cost of the upgrade over time while the crew is already on site.
A few practical tips if you're considering it:
Finance only the difference. Use the insurance funds for the covered work and look at financing for the upgrades you choose on top of that.
Decide early. Upgrade decisions are easiest to make before materials are ordered. Ask about financing when you're reviewing your estimate, not after the cabinets are installed.
Know your monthly comfort zone. Pick a monthly payment you're genuinely comfortable with, then build the upgrade list around it.
Read the terms. Rates, terms, and approval depend on the lender and your credit. Make sure you understand the details before you sign.
Upgrades homeowners often consider during a rebuild
Every home is different, but these are common places where people choose to go a step beyond the original:
Kitchens: upgraded countertops, soft-close cabinets, better lighting, or a more functional layout.
Bathrooms: a walk-in or tiled shower, a new vanity, or improved ventilation to help prevent future moisture problems.
Flooring: water-resistant luxury vinyl plank in kitchens, bathrooms, and laundry rooms.
Behind the walls: while walls are open, it can be a good time to address outdated plumbing or electrical, with a licensed professional's guidance.
Some of these choices, like water-resistant flooring or better bathroom ventilation, can also make your home more resilient if something goes wrong again.
Questions to ask before you decide
Before you add upgrades to your rebuild, it helps to sit down with your contractor and ask:
What does the insurance scope include, line by line?
What would this specific upgrade add to the cost?
Will the upgrade change the timeline?
What financing options are available, and how do I apply?
Clear answers to those questions will help you make a decision you feel good about long after the work is done.
Rebuild it better with Rapid Refurb
Rapid Refurb is a renovation and restoration company serving Greensboro, Randleman, Guilford County, and Forsyth County. We work with homeowners through the insurance rebuild process and can help you price upgrades separately, so you can see exactly what's covered and what's optional. If you'd like to explore financing through Lyon Financial or Service Finance, just ask when we review your estimate.
Ready to talk about your rebuild? Call us at 336-951-8534 or email estimates@igotrefurbed.com to schedule an estimate.


Comments